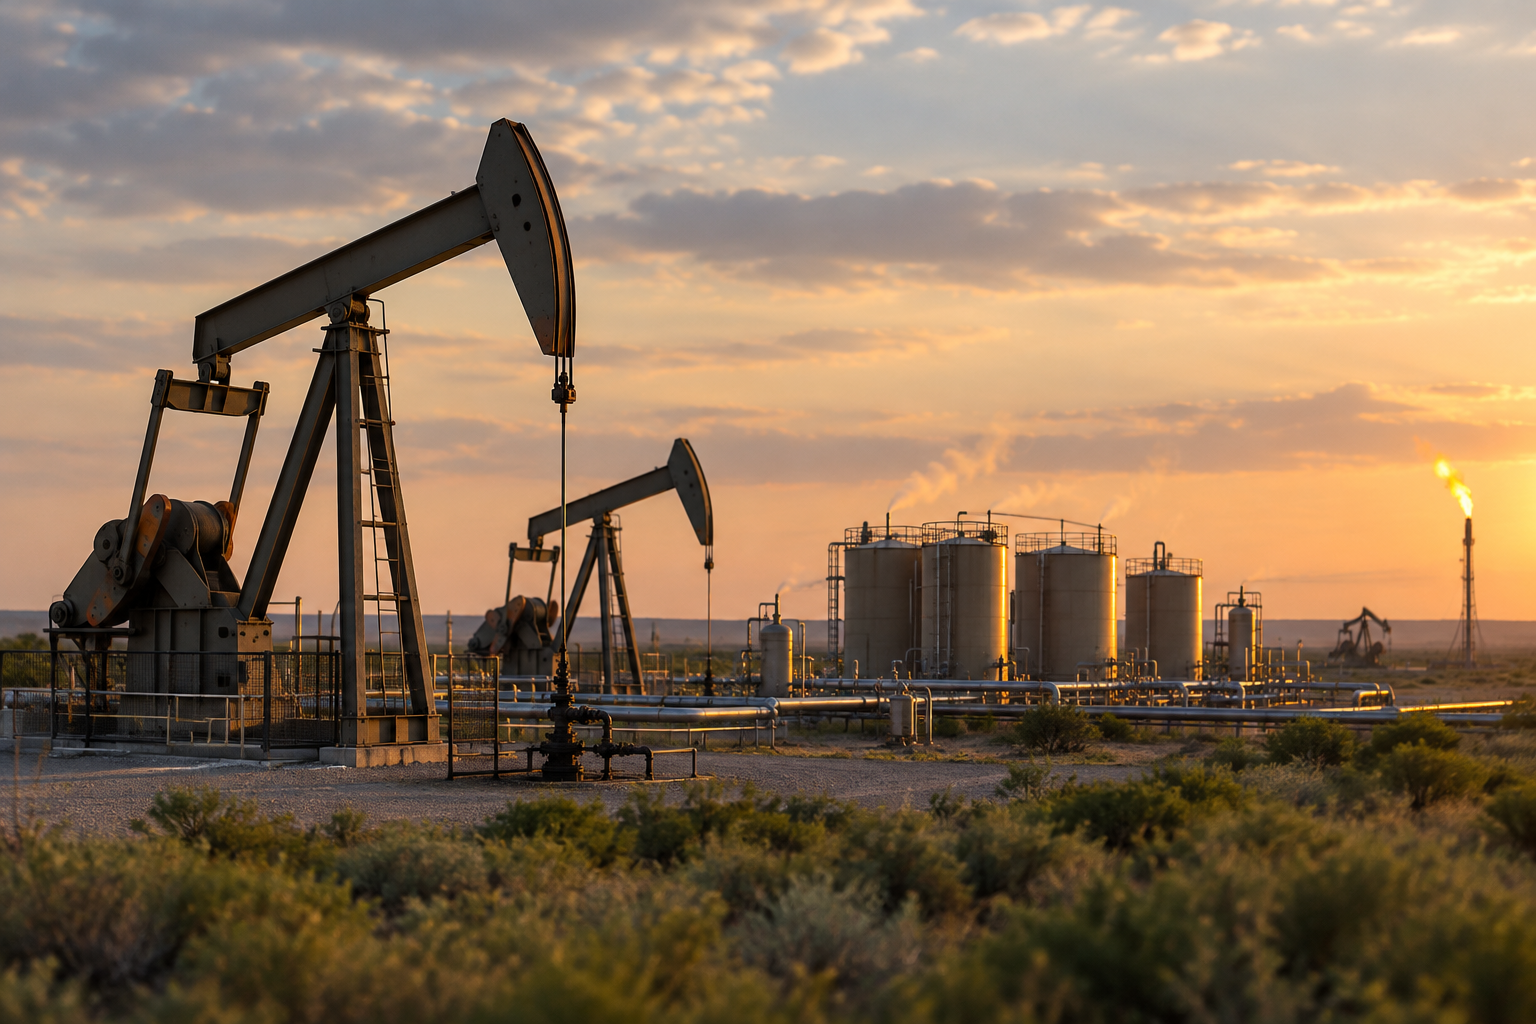
A $4.2 billion deal for a slice of the US shale industry says something important about where energy companies see value: Crescent Energy is buying Devon Energy’s Eagle Ford assets, while Devon is choosing to reshape its portfolio without selling the whole company. That distinction matters. In shale, the asset—not necessarily the corporate wrapper—has become the unit of strategy.
The transaction, announced as an agreement between Crescent and Devon, is therefore less a simple expansion story than a capital-allocation signal. Crescent is increasing its exposure to the Eagle Ford; Devon is monetizing a specific set of assets and repositioning its portfolio. (Because apparently the cleanest way to redraw the shale map is to move the pieces one basin at a time.)
The available details are deliberately limited: the deal is valued at $4.2 billion, and the supplied source does not provide production figures, reserves, funding details, transaction synergies, or closing conditions. That leaves investors with a useful constraint. The question is not whether the acquisition looks large in the abstract, but what each company is trying to accomplish by changing ownership of these assets.
Why an asset deal matters
A full-company acquisition would combine management teams, balance sheets, operating footprints and corporate strategies. An asset-level transaction is more targeted. It allows a buyer to increase exposure to a named basin while allowing the seller to adjust its portfolio without putting the entire enterprise on the negotiating table.
That structure fits the broader pattern of portfolio reshuffling among US energy producers. Companies can have different views on which assets deserve capital, how concentrated a portfolio should be, or where operating focus belongs. A property that is strategically important to one producer may be more valuable in the hands of another with a different portfolio design. The deal does not, by itself, establish that Crescent will generate operating synergies or that Devon’s remaining assets are stronger. It establishes that the two companies see different strategic value in ownership.
The oil-price backdrop
The supplied background also places the transaction against elevated oil prices linked to Middle East tensions. That context may be influencing both producer strategy and the valuation assigned to US shale assets. Higher crude prices can improve the appeal of oil-focused properties, while geopolitical uncertainty can make domestic production assets look strategically relevant to investors seeking exposure to energy markets.
But commodity conditions cut both ways. Energy equities remain sensitive to oil prices, and a higher spot-price environment does not remove the underlying volatility. The $4.2 billion valuation may reflect the market’s current view of oil, the Eagle Ford assets, or both; without additional financial and operating data, investors cannot sensibly separate those factors from the announcement alone.
What investors will focus on next
For Crescent, the immediate issue is increased Eagle Ford exposure. Investors will want future disclosures to clarify how that exposure fits within the company’s broader portfolio and capital-allocation priorities. The acquisition may strengthen Crescent’s position in the basin, but the supplied information does not establish the resulting production profile, reserves or financial impact.
For Devon, the question is what the asset sale says about the portfolio that remains. Divesting a business line can indicate a desire to concentrate on other assets, though the announcement by itself does not specify Devon’s rationale beyond the transaction. The market will ultimately need more detail to judge whether the sale represents disciplined portfolio management or simply a response to changing commodity conditions.
Set aside the prepared remarks for a moment, and the actual question is straightforward: does this deal create a more focused Crescent and a better-positioned Devon, or does it merely transfer exposure to a volatile oil market at a headline price of $4.2 billion? The answer will depend on operating and financial information not included in the initial announcement. For now, the transaction is best read as evidence that US shale ownership continues to move toward the companies most willing—or able—to hold particular assets through the next oil-price cycle.
Read the supplied report on Crescent Energy’s agreement to buy Devon Energy’s Eagle Ford assets.
Bull/Bear Verdict
Bull Case: The $4.2 billion asset transaction could give Crescent Energy greater Eagle Ford exposure while allowing Devon Energy to sharpen its portfolio, and elevated oil prices may support the strategic appeal of US shale assets.
Bear Case: The deal’s value cannot yet be tested against production, reserves, funding or synergies because those details are not supplied, while energy equities remain sensitive to oil prices and Middle East-driven volatility.